Swiss Banks Eye Broader Industry Collaboration for Tokenization Era
 Tomas Kauer - News Moderator
Switzerland’s early adoption of cryptocurrency trading and custody has given banks with practical experience in digital assets.
A new report by Blockstories, a European research and media company focused on digital assets, argues that these institutions will only maintain their lead on digital money and tokenization through broader market participation and joint efforts moving forward. These industry collaborations should seek to build infrastructure for new settlement networks and prepare for a potential central bank digital currency (CBDC).
The report, released in September 2026, looks at the state of crypto adoption in the Swiss banking sector, the diverse strategies employed in the sector, and emerging dynamics. It highlights how Switzerland managed to secure an early lead in crypto banking, while underscoring how developments such as new regulations and CBDC plans will cause future market shifts.
Collaborating to develop new applications
According to the report, the Swiss banking sector is expanding cooperation to develop new settlement networks as institutions seek to connect their customers to different markets and explore distributed ledger technology (DLT), digital assets, and tokenization.
Developing these networks requires institutions to collaborate and agree on how money moves between them, which rules apply and how the service connects to their existing operations.
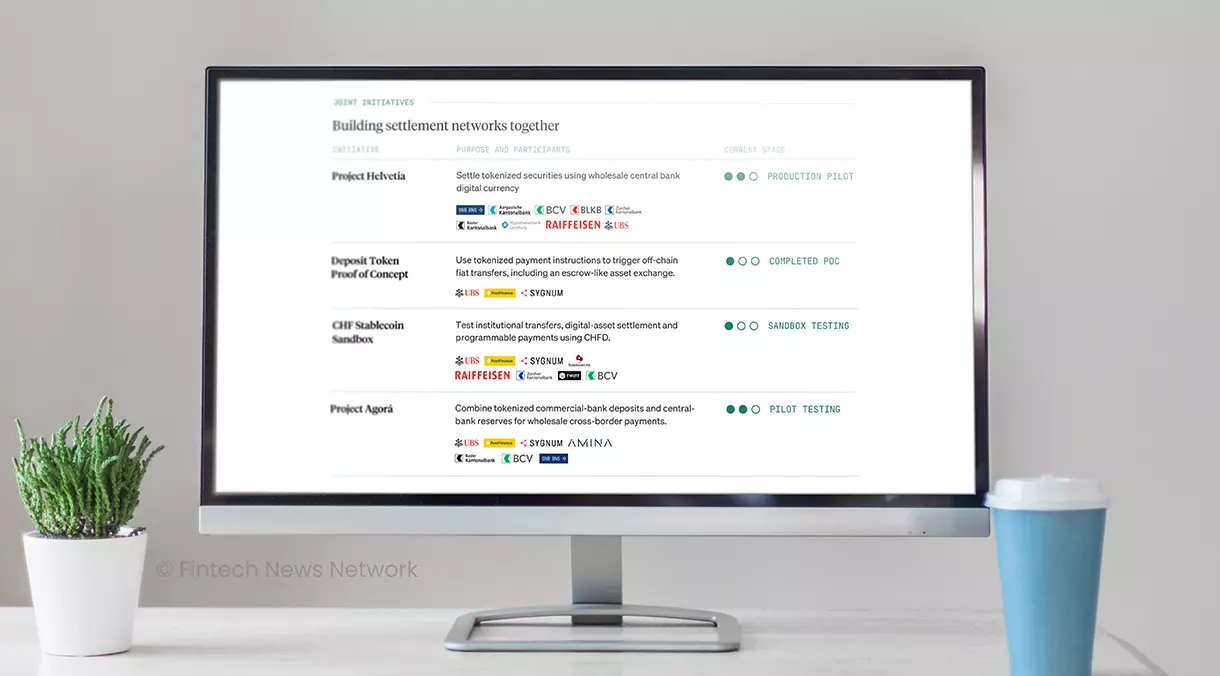
In this area, several joint initiatives are underway, covering securities settlement in CBDC, programmable payments via bank deposits, and stablecoins.
Project Helvetia, for example, is a joint initiative by the Swiss National Bank (SNB), the Bank for International Settlements (BIS) Innovation Hub, and the financial infrastructure operator SIX to test settling tokenized assets using central bank money on CBDC.
Launched in 2020, the initiative ranks among the Swiss financial sector’s most advanced projects on tokenization and CBDC. Now, in Phase III, Project Helvetia is piloting a CHF wholesale CBDC (wCBDC) on the SIX Digital Asset Platform, continuing until at least June 2028.
Another advanced effort is Project Agora, a public-private collaboration testing the desirability, feasibility and viability of a multi-currency shared programmable platform for wCBDC cross-border payments that brings together eight central banks, including those of five major reserve currencies, and over 40 leading financial institutions, including Switzerland’s SNB, SIX Group, Sygnum Bank, and UBS.
In July 2026, Project Agora conducted real-value testing (RVT) with 28 financial institutions and central banks across Asia, Europe and North America, completing transactions in a selection of currencies totaling approximately CHF 800,000. The program covered 17 transaction scenarios, with values ranging from CHF 9,000 to CHF 125,000 or local currency equivalents.
Other initiatives include a proof-of-concept (PoC) completed in September 2025 for a deposit token involving the Swiss Bankers Association (SBA), PostFinance, Sygnum Bank, and UBS. In April 2026, a consortium comprising UBS, PostFinance, Sygnum, Raiffeisen, Zurcher Kantonalbank, BCV, SIX, TWINT and Swiss Stablecoin launched a CHF stablecoin initiative to test selected use cases, including automated transactions between financial institutions and tokenized settlement of digital assets.

A digital Swiss franc
Another significant development in the Swiss digital asset space is the potential introduction of a CBDC. The report notes that while a digital form of the Swiss franc would give CHF-denominated stablecoins a potential audience among investors internationally, demand for the currency alone will not provide an issuer with enough revenue to cover operating costs. Hence, CHF issuers will need to find the right business model, with payments, foreign exchange (FX) and complementary banking services likely growing more central to the investment case.
In the crypto industry, several CHF stablecoin initiatives have emerged over the past years. For example, CHFAU is a Markets in Crypto-Assets Regulation (MiCAR)-compliant Swiss franc-backed stablecoin launched in February 2026 by AllUnity; Frankencoin (ZCHF) is a decentralized, on-chain collateralized stablecoin launched in 2023; CryptoFranc (XCHF) was a stablecoin introduced that Bitcoin Suisse which was eventually discontinued in 2024.
Swiss banks are also working together on a shared Swiss franc stablecoin model that blends distribution with joint testing in a sandbox setting.
A changing regulatory landscape
Globally, the crypto regulatory landscape is evolving at a fast pace. In Switzerland, the proposed payment instrument license for issuers of fiat-backed stablecoins would remove the fintech license’s CHF 100 million customer-funds ceiling, introduce specific requirements to protect clients funds in the event of insolvency, and permit risk-based secondary-market controls, including blacklisting. These changes aim to make Switzerland more appealing for stablecoin providers while strengthening consumer protection.
Though the Blockstories report argues that this reform would improve the route to scale stablecoins, it would also retain an additional organizational hurdle for banks. In particular, banks issuing the newly defined stablecoin category would need a separate entity and license.
Swiss banks’ digital assets, DLT strategies
In Switzerland, banks have adopted different strategies when it comes to digital assets and DLT. Global universal banks like UBS have embraced tokenization ahead of crypto access, prioritizing tokenized bonds, structured products, and money-market funds. These institutions are now collaborating with other industry stakeholders to develop payment and securities-settlement networks, focusing on building internal capabilities for their long-term tokenization strategy.
By contrast, domestic and retail banks like Swissquote, Postfinance, and Zurcher Kantonalbank, were early adopters of crypto banking products through services including as buy-and-hold trading, custody within online banking, and transfers. Through partnerships with specialist providers, they integrated cryptocurrencies into established banking relationships early on, a strategy that allowed them to retain funds and unlock new revenue streams.
Today, among Switzerland’s top 15 providers used by crypto holders, seven are domestic and retail banks, highlighting their role in the local crypto market. Swissquote and PostFinance rank fourth and sixth nationally, with 10% and 7% of Swiss crypto holders using these platforms in 2026, respectively.

Looking ahead, the Blockstories report expects these institutions to expand basic access to cryptocurrencies, and make selective investments in new financial applications, such as stablecoins, tokenized assets, and payment rails.
Finally, Swiss private banks were also early adopters of crypto services, targeting clients with crypto fortunes. Some started by accepting crypto transfers and providing lending, staking, and banking for crypto firms from the start, while others restricted themselves to execution-only trading or crypto-linked products.
Moving forward, more private banks are expected to add crypto-backed lending, expanding through relationship-led underwriting. Current providers will likely pursue higher loan-to-value ratios and larger facilities as they build operational knowledge.
For large private banks overseeing billions of Swiss francs across thousands of client portfolios, tokenization and smart contracts will add the most value by improving scalability in portfolio management, automating allocations and rebalancing, limiting idle cash between trades, and streamlining capital calls, interest payments and reconciliation.
Featured image: Edited by Fintech News Switzerland, based on image by magnific via Magnific
The post Swiss Banks Eye Broader Industry Collaboration for Tokenization Era appeared first on Fintech Schweiz Digital Finance News - FintechNewsCH.